DSCR Loan Realtor in Philadelphia

Investor friendly REALTOR helping Philadelphia investors find rentals that qualify for DSCR loans, underwrite the ratio before offering, and close with confidence.

DSCR lenders qualify the property, not your paycheck. I help you find deals where the rent actually covers the debt so the loan approves and the property performs.

Call or Email Nicholas Davis

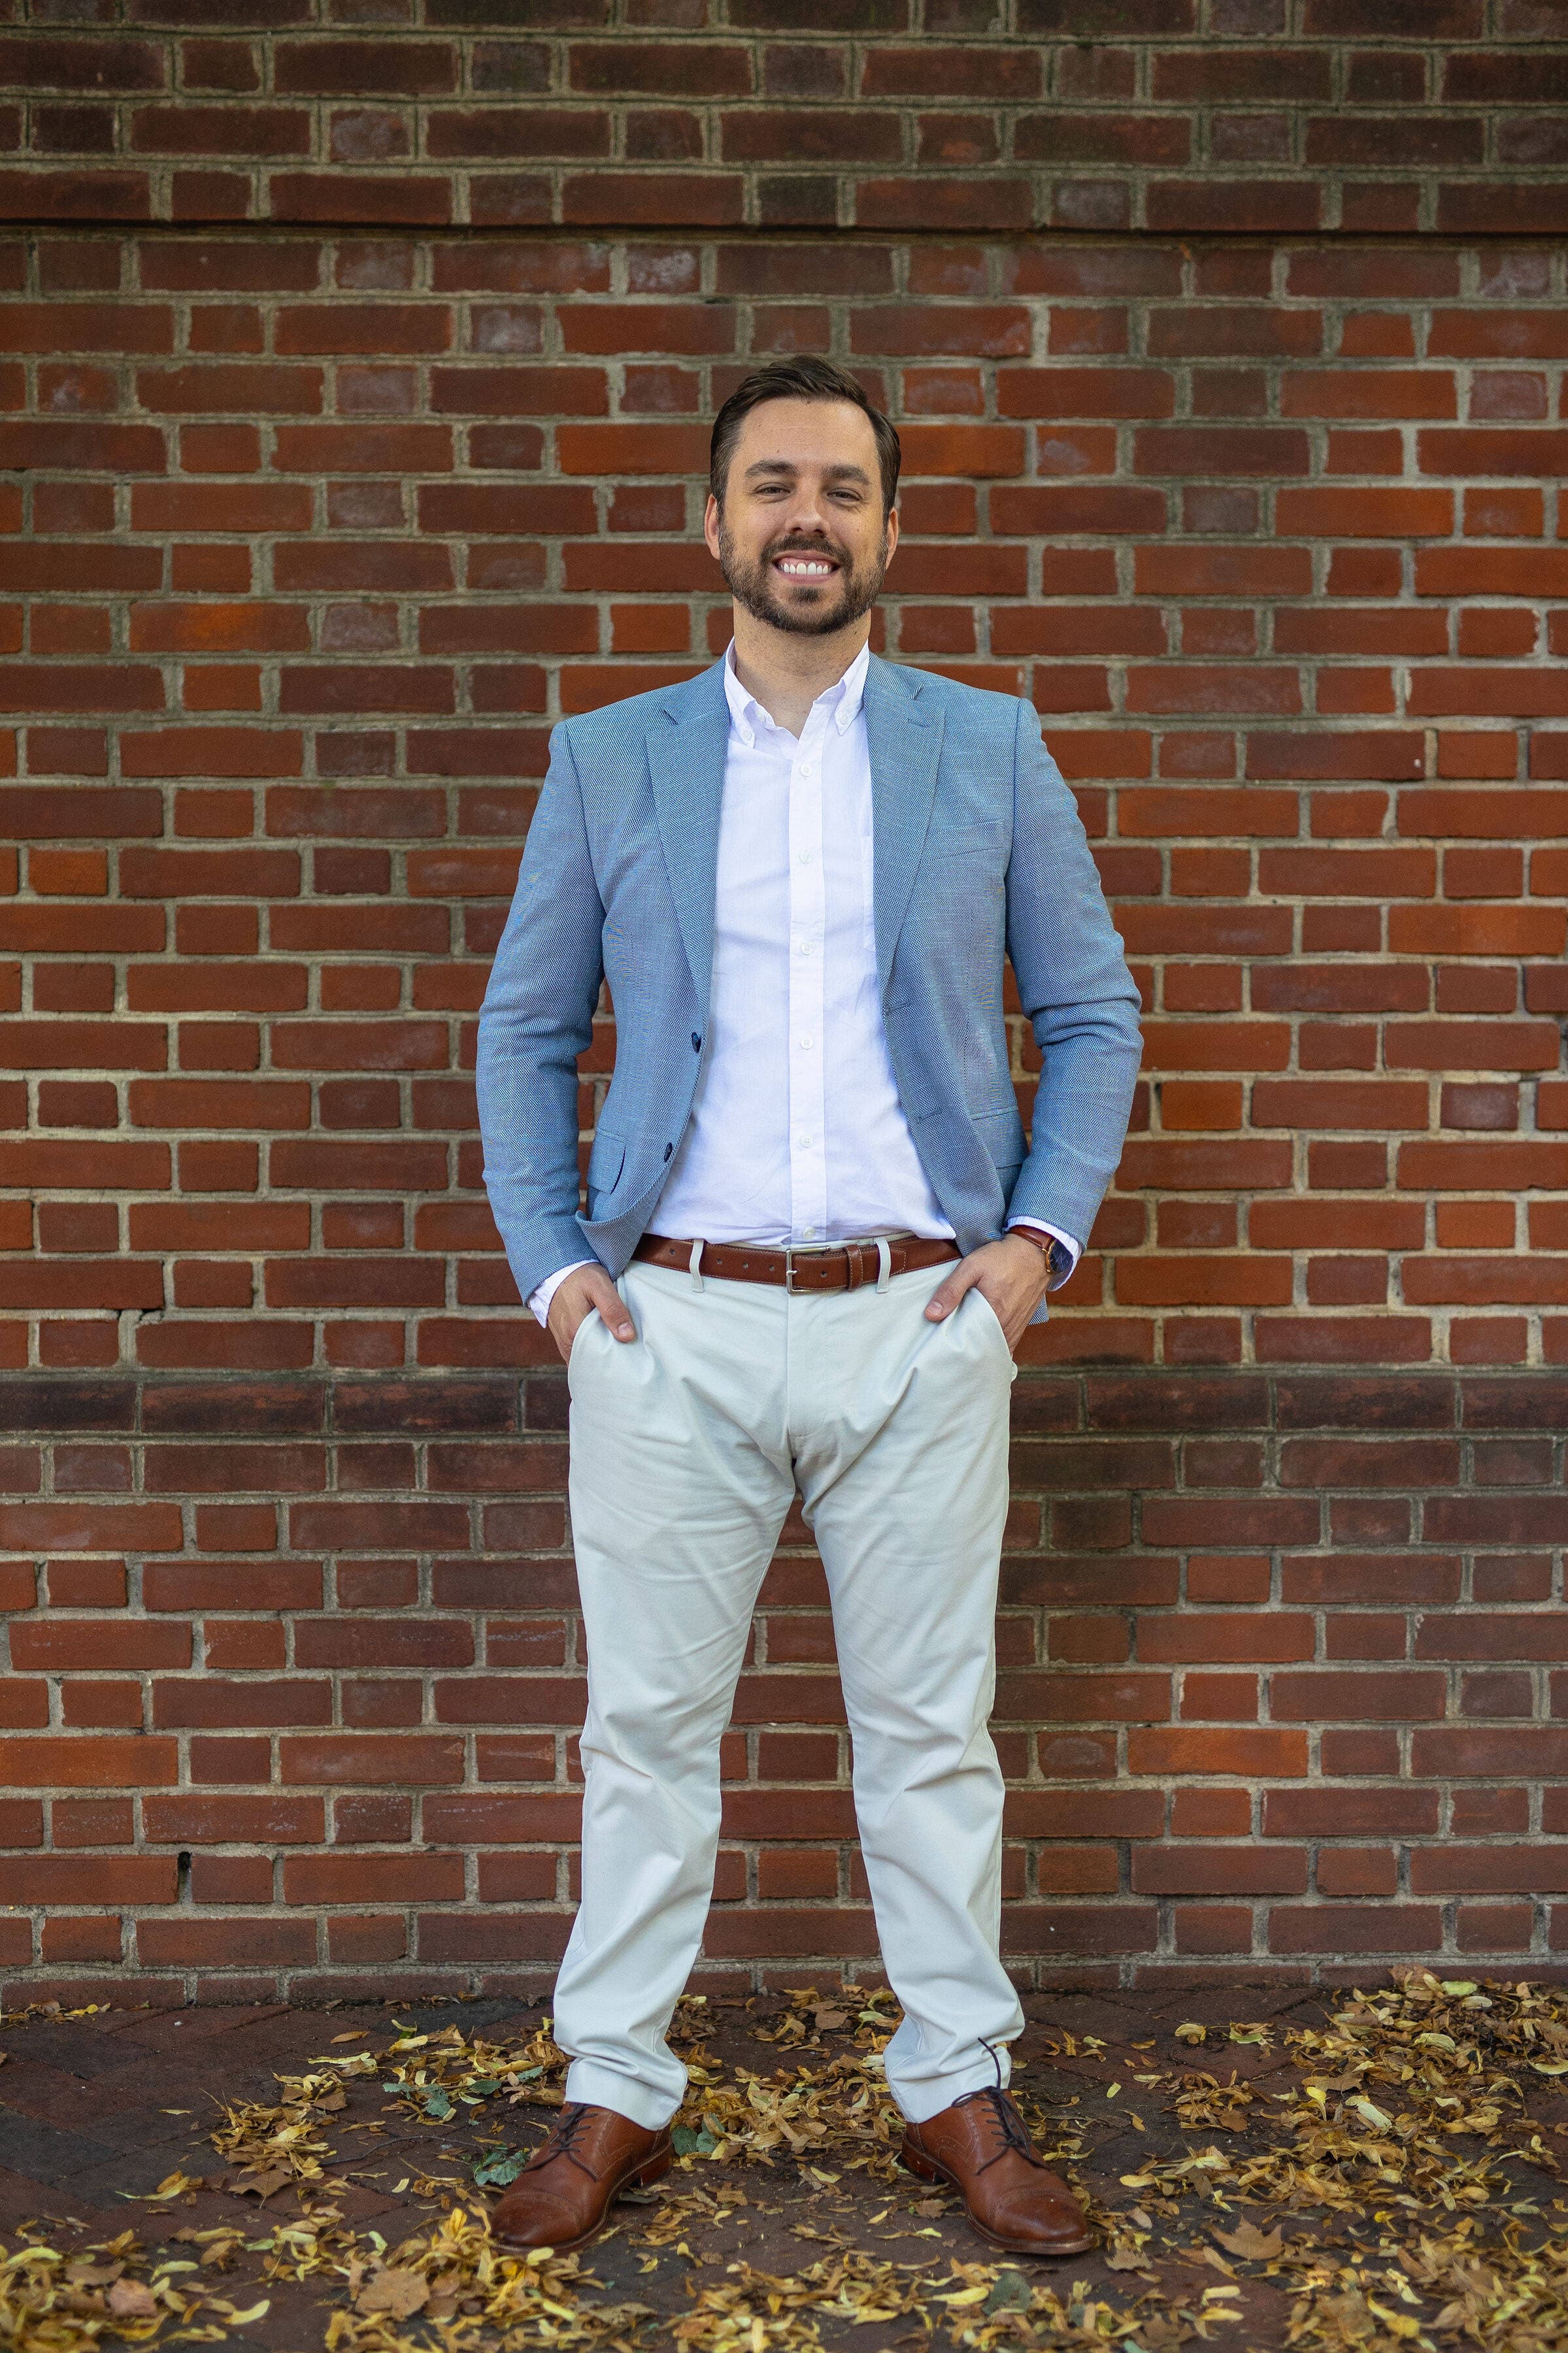
Nicholas Davis, DSCR loan investor friendly real estate agent in Philadelphia

Trusted by buyers, sellers, and investors with experience built in the field

  • In Team Sales

    $500M+

    Total Sales Volume
  • Buyers & Sellers Helped

    1000+

    Clients Served to Date
  • Philadelphia Metro

    650+

    Total Transactions
  • Combined Team Experience

    22+

    Combined Years of Experience

Find the Property That Qualifies, Not Just the Lender

A DSCR loan approves or dies on one number: whether the property's net operating income covers the mortgage by the lender's minimum, usually 1.25. Plenty of agents can send you listings, but the deal is lost if the rent to price ratio does not support the loan. I underwrite the DSCR before you write an offer, help you target the multi unit and strong rent blocks in Philadelphia where the ratio works, and keep the appraisal rent schedule realistic so there are no surprises at closing.

Dscr Math

The numbers a DSCR lender will check

DSCR underwriting is simple arithmetic with unforgiving inputs. These are the three numbers I pressure test on every deal before you commit.

Debt Service Coverage Ratio (DSCR)

How a lender checks the rent covers the loan

The debt service coverage ratio compares a property's net operating income to its annual mortgage payments. DSCR lenders use it instead of personal income to qualify investors, and most want a ratio of 1.25 or higher.

Formula
DSCR = NOI ÷ Annual Debt Service
NOI
Net Operating Income
Annual Debt Service
Twelve months of principal and interest on the loan

Example: An NOI of $14,060 against $11,000 in yearly loan payments is a DSCR of 1.28, which clears the common 1.25 lender floor.

Net Operating Income (NOI)

What the property earns before the mortgage

Net Operating Income is the annual income a rental property produces after vacancy and all operating expenses are subtracted, but before debt service and income taxes, making it the cleanest way to compare how two properties actually perform.

Formula
NOI = Gross Rental Income − Vacancy − Operating Expenses
Gross Rental Income
All rent and fees collected over twelve months
Vacancy
Expected lost rent between tenants, often 5 to 8 percent
Operating Expenses
Taxes, insurance, water, maintenance, management, turnover, reserves

Example: $24,000 in rent, minus $1,440 vacancy, minus $8,500 in expenses leaves an NOI of $14,060.

Cash Out Refinance

Pulling your capital back out of a stabilized rental

A cash out refinance replaces your existing financing with a larger loan based on the property's new appraised value, and the difference is paid to you in cash. In a BRRRR deal it is the step that recovers the capital for the next purchase.

Formula
Cash Out = (Appraised Value × LTV) − Existing Loan Payoff − Closing Costs
Appraised Value
Post renovation appraisal, closely tied to ARV
LTV
Lender's loan to value limit, typically 70 to 80 percent on rentals

Example: $300,000 appraisal × 0.75 = $225,000. Pay off a $180,000 loan and $6,000 in costs, and $39,000 comes back out.

Process

How We Help You Invest in Philadelphia

A disciplined investing process for Philadelphia — from deal sourcing and underwriting to execution and exit planning.

  1. 01

    Search Philadelphia On-Market and Distress Properties Using Compass One

    Identify on-market opportunities in Philadelphia through Compass One that match your strategy, timeline, and target returns.

    Compass One
  2. 02

    Run 70% Rule And/Or DSCR Analysis

    Underwrite each deal with the right framework for your strategy, including 70% rule for flips and DSCR analysis for rentals.

  3. 03

    Validate Comps And Build Budget

    Confirm after-repair value and create a realistic project budget covering renovation scope, holding costs, reserves, and exit costs.

  4. 04

    Structure Offer And Terms

    Prepare a disciplined offer with contingencies, timelines, and pricing terms that protect your downside while staying competitive in Philadelphia.

  5. 05

    Complete Due Diligence And Financing

    Coordinate inspections, contractor walk-throughs, lender requirements, and title review so your numbers hold through closing.

  6. 06

    Execute Renovation Or Lease-Up Plan

    Move from closing to execution with a clear operating plan for rehab, leasing, refinance, or resale based on your investment objective.

About Me

Built by Real Experience

More than 10 years in real estate investing, property operations, and construction execution now power every client strategy.

Philadelphia Real Estate Realtor, Investor, and Licensed General Contractor at

Compass
Nicholas Davis with Jett

Nicholas Davis brings more than 10 years of hands on real estate experience across investing, property management operations, renovation planning, and project execution. Long before becoming a licensed real estate agent, he was already evaluating deals, managing risk, and protecting margins in the field.

That operating background gives clients an advantage at every stage. You get practical guidance on pricing, renovation scope, hold costs, rental upside, negotiation structure, and timeline decisions, all grounded in real world execution.

Today, as a full time Philadelphia real estate agent and licensed general contractor, Nicholas helps buyers, sellers, and investors make stronger decisions with clarity and confidence. No pressure. No fluff. Just direct advice and disciplined strategy focused on results.

Real Estate Guides for Philadelphia

Practical real estate guides for buyers, sellers, and investors, focused on decisions that matter most in your market.

Dscr Faq

DSCR loan questions Philadelphia investors ask

Straight answers on how DSCR loans work, what ratio you need, where they fit in Philadelphia, and how I help investors find properties that qualify.

  1. What is a DSCR loan?

    +×

    A DSCR loan is an investment property mortgage that qualifies you based on the property's rental income instead of your personal income or tax returns. The lender divides the property's net operating income by the annual mortgage payment to get the debt service coverage ratio, and if that ratio clears their minimum, the deal can move forward without W2s or debt to income calculations. Read what DSCR means in real estate.

  2. What DSCR ratio do I need to qualify?

    +×

    Most lenders use 1.25 as the qualifying floor, meaning the property produces $1.25 of income for every $1.00 of debt service. Some programs go as low as 1.0 or even below with a larger down payment and higher rate, but those deals are fragile. For a healthier operating cushion in a market like Philadelphia, I like to see 1.30 to 1.40 when the plan is a long term hold. See what a good DSCR ratio looks like.

  3. Do DSCR loans work in Philadelphia?

    +×

    Yes, and Philadelphia is one of the better East Coast markets for them because entry prices are still reasonable relative to rent. The ratio works most often on duplexes and triplexes, on rowhomes in strong rental blocks, and on properties where the rent to purchase price relationship is favorable. It rarely works on expensive single family homes in appreciation driven neighborhoods, which is exactly why targeting the right product matters. DSCR loans for Philadelphia investors.

  4. How much do I need to put down on a DSCR loan?

    +×

    Twenty percent down is possible on some programs, but many Philadelphia deals end up at 25 percent or more once the lender weighs the ratio, your credit, reserves, and the property type. Lower ratios and older housing stock tend to push the down payment up. I model the likely down payment and reserves early so you know the real cash to close before you fall in love with a property. Are all DSCR loans 20 percent down?.

  5. How do you help me find a property that qualifies for a DSCR loan?

    +×

    I start from the lender's math and work backward to a buy box. Given your down payment, the current DSCR rate, and the lender's minimum ratio, I can tell you the maximum price that works at a given rent. Then we target neighborhoods and property types in Philadelphia where that relationship actually exists, verify the rent with real comparable leases rather than listing claims, and underwrite the full NOI with realistic taxes, insurance, water, vacancy, and maintenance so the appraisal rent schedule does not surprise you. Step by step DSCR qualification.

  6. What are the downsides of a DSCR loan?

    +×

    Cost and constraint. Rates and fees usually run higher than conventional financing, prepayment penalties are common, and the approval depends almost entirely on supportable rent. If the appraiser's rent schedule comes in low or the property needs more work than expected, the ratio can fall below the floor and the deal can stall. Those risks are manageable when the underwriting is disciplined, which is where I spend most of my time with DSCR buyers. The downside of a DSCR loan.

  7. Can I use a DSCR loan for the refinance step of a BRRRR deal?

    +×

    Yes, and it is one of the most common pairings. After the rehab and lease up, a DSCR cash out refinance lets you pull capital out based on the new appraised value and the in place rent, without personal income documentation. The key is making sure the stabilized NOI covers the new, larger loan at the lender's ratio. I model that refinance before you buy so the exit is real, not hopeful. See my BRRRR strategy services.

  8. How do I start a DSCR purchase with you?

    +×

    Share your down payment, credit range, the rate quote or lender you are working with, and the kind of property you want to own. From there I build a buy box around the ratio, line up properties in Philadelphia where the math works, and stay close through underwriting, inspection, appraisal, and closing. If you do not have a DSCR lender yet, I can point you to ones that are active in this market. Book a DSCR consultation.

Contact

Book Your Consultation

Tell me a little about your goals and I will reach out to discuss your next move in the market.

Nicholas Davis

Nicholas Davis

Currently Online

What you can expect:

  • Tailored strategy for buying or selling
  • Neighborhood-level market guidance
  • Seamless communication from start to close
  • Disciplined execution that protects your position

Contact form

Affiliations and Tools I Work With

  • Compass logo
  • Redfin logo
  • MLS Realtor logo
  • Google Workspace logo
  • DocuSign logo
  • ChatGPT logo